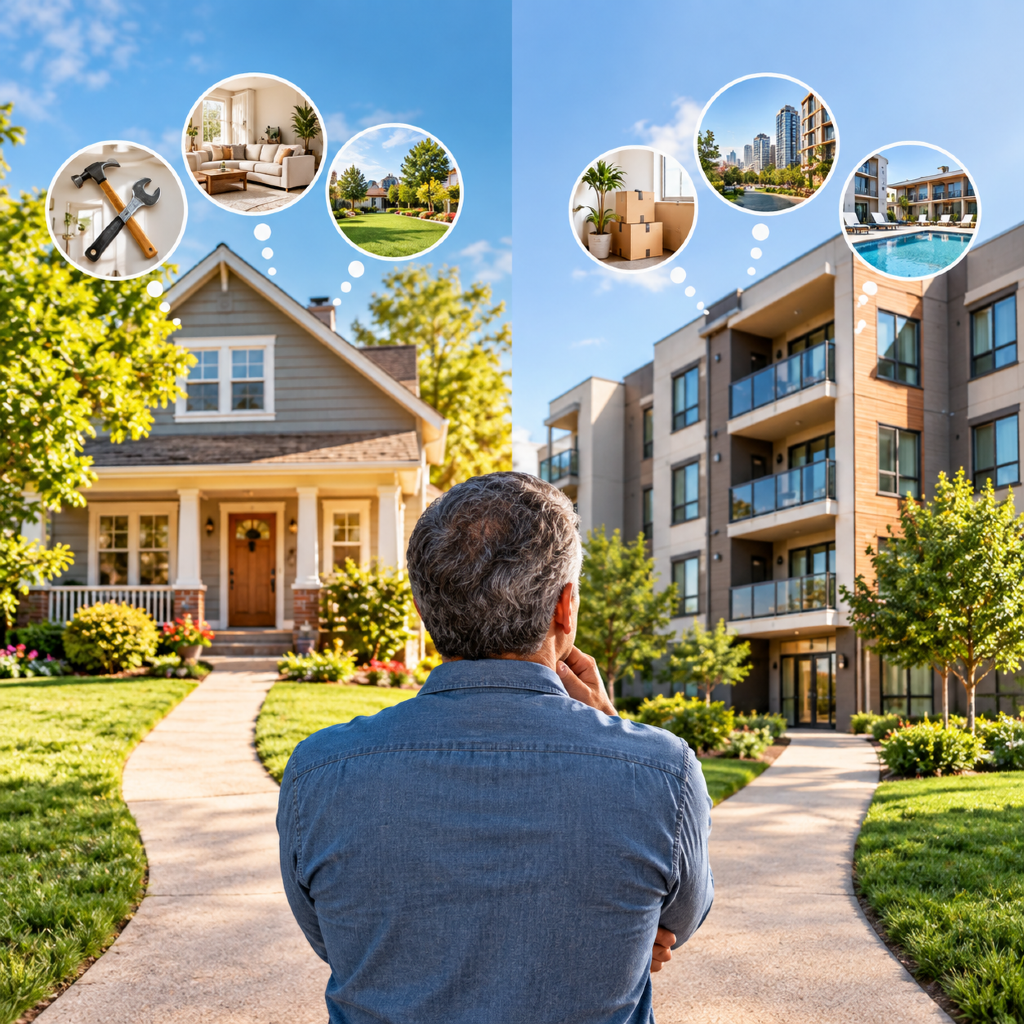
Key Takeaways
- Renting and buying each have distinct benefits, costs, and responsibilities that suit different personal needs.
- Careful evaluation of financial stability, lifestyle, and market trends is essential before making a decision.
Making the choice between renting and buying a home is a major step, one that impacts your lifestyle and finances for years to come. In this guide, you’ll discover the main differences between renting and buying, weigh their advantages and disadvantages, and learn how to assess which option aligns best with your personal situation.
What Does It Mean to Rent or Buy?
Understanding the Renting Process
When you rent, you agree to lease a property from a landlord for a set period—often a year—paying monthly rent in exchange for the right to live there. You typically sign a lease, which details your responsibilities and rights as a tenant. Renters are generally not responsible for major maintenance or repairs; that falls to the property owner. Additionally, you may need to pay a security deposit and follow property rules, such as restrictions on modifications or having pets.
How Home Buying Works
Buying a home involves purchasing property, either with your own funds or through a home loan (mortgage). This process can include finding a suitable property, making an offer, securing financing, and completing a closing process. As the homeowner, you’re responsible for all maintenance, taxes, insurance, and any value changes due to the housing market. Homeownership grants you the freedom to personalize your space, but it also comes with longer-term financial and legal commitments.
What Key Factors Affect Your Choice?
Financial Stability Considerations
Your current financial health is one of the most significant factors. To buy, you typically need stable income, a solid credit history, a down payment, and additional funds for closing costs and ongoing responsibilities such as taxes and repairs. Renting, meanwhile, generally requires less upfront cash. Think about your income predictability, ability to cover unexpected expenses, and readiness for long-term financial obligations before making a decision.
Lifestyle and Flexibility Needs
Ask yourself if you prioritize flexibility or stability. Renting can be well-suited for those who might need to relocate for work, family, or lifestyle changes. Lease terms are shorter and moving between properties is easier compared to selling a home. Buying is often chosen by those seeking rootedness, customization, and a sense of long-term investment in their community.
Market and Location Influences
Real estate markets vary widely by area. Home prices, rent levels, and housing demand all fluctuate, very often impacting the financial aspects of your decision. In areas where home values are rising steadily, buying may offer equity growth, while in markets with high prices or instability, renting could help you avoid financial risk. Consider local property values, the job market, and neighborhood development plans before choosing.
What Are the Pros of Buying a Home?
Building Equity
As you pay off your mortgage, you build equity—an ownership stake in your home. Over time, this can boost your net worth and offer the potential for future financial security if property values rise. Unlike rent payments, which do not contribute to your assets, mortgage payments build your ownership.
Potential for Personalization
Homeownership allows you to tailor your space—from painting walls to renovating rooms. These changes not only reflect your personal style but may also enhance property value. You have more freedom to create the home environment that suits your needs.
Long-Term Stability
Owning your home gives you consistent housing costs if you have a fixed-rate mortgage. You’re also protected from unexpected lease terminations or rent increases, and you have a greater sense of control over your living situation.
What Are the Cons of Buying?
Upfront and Ongoing Costs
Buying requires a significant initial investment, including a down payment (often 10-20% of the purchase price), closing costs, and moving expenses. Ongoing, you’ll need to cover property taxes, homeowners’ insurance, maintenance, repairs, and, for some, homeowners’ association fees. These costs can add up and should be planned for carefully.
Market Risk Factors
Home values can fluctuate due to local and national economic trends. There’s always the risk that your property value may decline, which could affect your ability to sell or refinance in the future. It’s vital to understand that real estate is an investment that can gain but also lose value.
Responsibility for Repairs
All repairs and maintenance fall to you as the homeowner. This includes both expected costs like appliance replacement and unexpected issues like plumbing leaks or roof repairs. Setting aside funds for home upkeep helps minimize financial strain.
What Are the Pros of Renting?
Lower Initial Commitment
Renting generally requires less money up front. Most landlords request a security deposit and your first month’s rent, making this option more accessible if you haven’t saved for a large down payment. You also avoid many transaction-related fees, like closing costs.
Flexibility to Relocate
Leases usually last only 12 months or less, so it’s easier to move if your job or personal needs change. This flexibility is valuable for people uncertain about their long-term plans or those anticipating future moves.
Limited Maintenance Duties
Renters are usually not responsible for significant repairs or ongoing maintenance. If a major appliance breaks or the roof leaks, your landlord typically manages and pays for the repair, reducing your financial exposure from unexpected issues.
What Are the Cons of Renting?
No Equity Accumulation
Rent payments do not add to your assets. Instead, they are exchanged for the right to occupy a space, with no future ownership stake or return when you move. This can make it harder to build wealth over time compared to homeownership.
Potential for Rent Increases
Landlords can raise rent when your lease renews, sometimes unpredictably if the rental market is competitive. Rent increases can affect your budget and potentially force you to move if costs become too high.
Restrictions on Changes
Most rentals limit how much you can personalize or update. Major alterations often require landlord approval, so you may not be able to fully adapt the space to your preferences.
How Can You Decide What’s Right?
Assessing Your Priorities
Begin by clarifying your non-negotiables. Is flexibility more important than building equity? Do you want to settle in an area for a long time, or might you need to move soon? Making a list of your personal, financial, and lifestyle priorities can reveal which option aligns with your goals.
Calculating Financial Impact
Take a close look at your budget. Compare the overall costs of renting and buying in your area, factoring in all associated expenses and potential savings. Online calculators and financial advisors can help estimate long-term costs, but always remember these tools provide estimates, not predictions.
Thinking Long-Term
Consider not only your current needs, but where you hope to be in several years. Are you ready for a long-term commitment in one place, or is it likely your career or family situation might change? Your stage of life plays a major role in the decision, as does your willingness to accept certain levels of responsibility, risk, and reward.