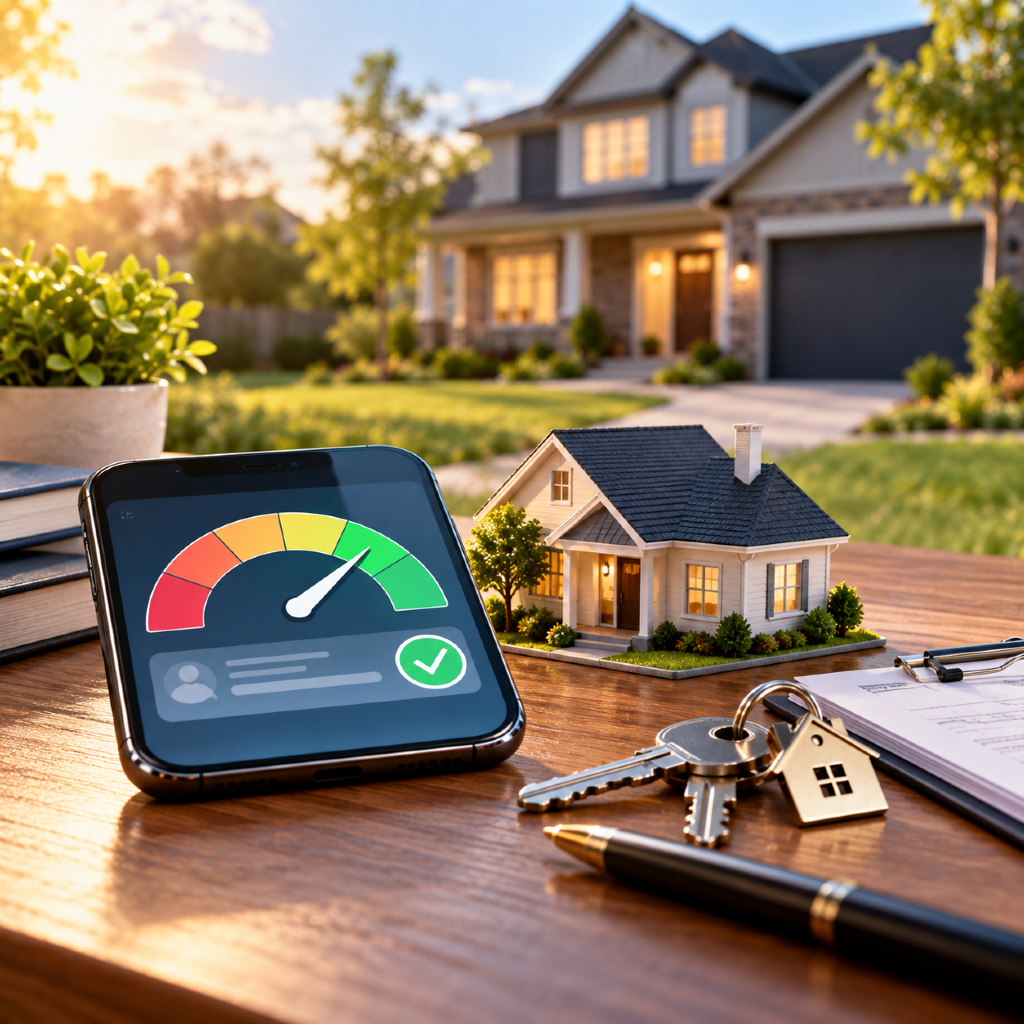
Credit Score Needed to Buy a House: Key Requirements and Buyer Questions

Key Takeaways Your credit score is crucial for mortgage eligibility and can influence your loan terms and options. Improving your credit and understanding additional approval factors can make home buying more attainable. ...

Key Takeaways

  • Your credit score is crucial for mortgage eligibility and can influence your loan terms and options.
  • Improving your credit and understanding additional approval factors can make home buying more attainable.

Thinking about buying a home but uncertain about your credit score? Understanding how your credit profile affects mortgage eligibility is essential. This guide breaks down key requirements, helps answer your top questions, and offers guidance on strengthening your mortgage application.

What Is a Credit Score?

Credit score basics

A credit score is a three-digit number that gives lenders a quick snapshot of your creditworthiness. It helps them evaluate how likely you are to repay borrowed money based on your history of managing debt. Scores typically range from 300 to 850, with higher numbers signaling more reliable borrowing habits.

Credit scores are commonly pulled from major bureaus such as Equifax, Experian, and TransUnion. For mortgages, the FICO Score is often referenced, though some lenders may consider other scoring models.

How credit scores are calculated

Credit scores are based on the information in your credit report. The main factors include:

  • Payment history (on-time or late payments)
  • Amounts owed (your overall debts and credit utilization)
  • Length of credit history (how long you’ve used credit)
  • Types of credit (mix of cards, loans, and accounts)
  • New credit (recent applications or new accounts)

Each factor is weighted differently, but timely payments and responsible credit use are always critical.

Why Does Your Credit Score Matter?

Impact on mortgage eligibility

Lenders use your credit score as a key indicator when deciding whether to approve your mortgage application. A higher score signals less risk, potentially making your path to approval smoother. Conversely, a lower score might require additional documentation, a larger down payment, or lead to application denial.

Connection to loan terms

Your credit score doesn’t just impact approval—it also affects your loan’s terms. Higher scores can result in more favorable rates, lower fees, and broader loan choices. If your score is lower, you might face higher costs over the life of your mortgage or need to meet stricter conditions.

What Credit Score Do Lenders Require?

Typical score ranges for mortgages

There isn’t a universal minimum score for all home loans, but general guidelines exist:

  • 620+: Often the minimum for conventional mortgages.
  • 580+: Frequently needed for certain government-backed loans.
  • 500–579: Some programs may permit approvals, typically with higher down payments or stricter conditions.

A higher score offers you more flexibility. However, exceptions are possible based on the full picture of your finances.

Conventional vs. government-backed loans

Conventional loans are offered by private lenders and generally require higher credit scores, most often starting at 620.

Government-backed loans, such as FHA, VA, and USDA programs, usually have lower minimum score requirements:

  • FHA loans may accept scores as low as 580, or even 500 with larger down payments.
  • VA loans and USDA loans often consider applicants with scores in the low- to mid-600s, with other eligibility criteria applying.

Each loan type is designed for different needs, and lenders may set stricter criteria than program minimums.

Can You Buy a House With Bad Credit?

Options for lower credit scores

If your credit score is below typical thresholds, you may still have opportunities:

  • Some government-backed loans are more flexible on minimum scores.
  • Providing a larger down payment can sometimes offset a lower score.
  • Having a strong employment record or higher income may help balance your application.

Some lenders offer programs for buyers with credit challenges, but these usually require careful consideration due to potentially higher rates or fees.

Potential challenges for buyers

Buying a house with bad credit often means facing additional hurdles:

  • You may qualify for fewer loan options.
  • Down payment and income requirements may be higher.
  • You could pay more in interest over the life of the loan.

If your score is low, it’s wise to compare all available paths and understand the long-term costs before moving forward.

What Other Factors Affect Approval?

Income and employment

Stable, verifiable income plays a major role in loan approval. Lenders review your job history, income sources, and likelihood of continued employment. Having steady work and consistent pay makes you a more attractive applicant.

Debt-to-income ratio

Your debt-to-income (DTI) ratio measures how much of your monthly income goes toward debts. Most lenders look for a DTI below 43%, though some programs may allow higher ratios if you have other compensating strengths. A lower DTI shows you can manage new payments without overextending.

Down payment considerations

Your down payment size can influence loan approval and terms. A larger down payment often reduces the lender’s risk, which can help offset a lower credit score or make your application more competitive. While many programs require a minimum percentage, putting down more is usually viewed favorably.

How Can You Improve Your Credit Score?

Building credit before buying

If your credit needs improvement, even small steps can make a big difference:

  • Make all payments on time, every time.
  • Pay down credit card balances and reduce overall debt.
  • Avoid opening too many new accounts at once.
  • Monitor your credit reports for errors and dispute inaccuracies promptly.

These habits can help build a stronger profile over several months, improving your chances for better loan terms.

Common mistakes to avoid

To maintain or raise your score as you prepare to buy a house, try to avoid:

  • Missing payments or paying late.
  • Maxing out credit cards or taking on large new debts.
  • Applying for multiple forms of credit in a short time, which can temporarily lower your score.

Focusing on steady, responsible use of credit is the best long-term strategy.
Lorem ipsum dolor sit amet, consectetur adipiscing elit. Ut elit tellus, luctus nec ullamcorper mattis, pulvinar dapibus leo.

Secondary Heading Text

Sed ut perspiciatis unde omnis iste natus error sit voluptatem accusantium doloremque laudantium, totam rem aperiam, eaque ipsa quae ab illo inventore veritatis et quasi architecto beatae vitae dicta sunt explicabo. Nemo enim ipsam voluptatem quia voluptas sit aspernatur aut odit aut fugit, sed quia consequuntur magni dolores eos qui ratione voluptatem sequi nesciunt. Nemo enim ipsam voluptatem quia voluptas sit aspernatur aut odit aut fugit, sed quia consequuntur magni dolores eos qui ratione voluptatem sequi nesciunt.

Lorem ipsum dolor sit amet, consectetur adipiscing elit. Ut elit tellus, luctus nec ullamcorper mattis, pulvinar dapibus leo.

Recent Articles

Related Ebooks

Guide to buying your first Home

Download the Free E-Book

If you’re thinking about buying a home, then you won’t want to miss out on our comprehensive E-Book. Our E-Book offers practical advice and insider tips from experienced professionals in the real estate industry.

Sed ut perspiciatis unde omnis iste natus error sit voluptatem accusantium doloremque laudantium, totam rem aperiam, eaque ipsa quae ab illo inventore veritatis et quasi architecto beatae vitae dicta sunt explicabo. Nemo enim ipsam voluptatem quia voluptas sit aspernatur aut odit aut fugit, sed quia consequuntur magni dolores eos qui ratione voluptatem sequi nesciunt. Nemo enim ipsam voluptatem quia voluptas sit aspernatur aut odit aut fugit, sed quia consequuntur magni dolores eos qui ratione voluptatem sequi nesciunt.

Sed ut perspiciatis unde omnis iste natus error sit voluptatem accusantium doloremque laudantium, totam rem aperiam, eaque ipsa quae ab illo inventore veritatis et quasi architecto beatae vitae dicta sunt explicabo. Nemo enim ipsam voluptatem quia voluptas sit aspernatur aut odit aut fugit, sed quia consequuntur magni dolores eos qui ratione voluptatem sequi nesciunt. Nemo enim ipsam voluptatem quia voluptas sit aspernatur aut odit aut fugit, sed quia consequuntur magni dolores eos qui ratione voluptatem sequi nesciunt.

Secondary Heading Text

Sed ut perspiciatis unde omnis iste natus error sit voluptatem accusantium doloremque laudantium, totam rem aperiam, eaque ipsa quae ab illo inventore veritatis et quasi architecto beatae vitae dicta sunt explicabo. Nemo enim ipsam voluptatem quia voluptas sit aspernatur aut odit aut fugit, sed quia consequuntur magni dolores eos qui ratione voluptatem sequi nesciunt. Nemo enim ipsam voluptatem quia voluptas sit aspernatur aut odit aut fugit, sed quia consequuntur magni dolores eos qui ratione voluptatem sequi nesciunt.

Sed ut perspiciatis unde omnis iste natus error sit voluptatem accusantium doloremque laudantium, totam rem aperiam, eaque ipsa quae ab illo inventore veritatis et quasi architecto beatae vitae dicta sunt explicabo. Nemo enim ipsam voluptatem quia voluptas sit aspernatur aut odit aut fugit, sed quia consequuntur magni dolores eos qui ratione voluptatem sequi nesciunt. Nemo enim ipsam voluptatem quia voluptas sit aspernatur aut odit aut fugit, sed quia consequuntur magni dolores eos qui ratione voluptatem sequi nesciunt.

Latest Articles

Credit Score Needed to Buy a House: Key Requirements and Buyer Questions

Key Takeaways Your credit score is crucial for mortgage eligibility

How to Save for a Home Down Payment: Best Practices and Key Considerations

Key Takeaways Start saving early using automated strategies and clear

Case Study: Using a Home Buying Checklist to Avoid Buyer Mistakes

Key Takeaways A tailored checklist helps safeguard your home buying

Best Agents Near You

Can’t Find Your Agent? Only work with the best
profile_pic

Alec Warner

South San Francisco, California
profile_pic

Antonio Dobbs

Jacksonville, Florida
profile_pic

Brenda Walker

Gilbert, Arizona
profile_pic

Brian Duncan

El Paso, Texas
profile_pic

Brittany Lopez

Las Vegas, Nevada
profile_pic

Calvin Patterson

Lincoln, Nebraska
profile_pic

Carly Brooks

Philadelphia, Pennsylvania
profile_pic

Charles Evans

Washington, District of Columbia
profile_pic

Christina Boyd

Scottsdale, Arizona
profile_pic

Daniel Rios

Madison, Wisconsin
profile_pic

Danielle Richardson

Tempe, Arizona
profile_pic

David Donovan

Oklahoma City, Oklahoma
profile_pic

David Russell

Amarillo, Texas
profile_pic

Dawn Stout

Winston-Salem, North Carolina
profile_pic

Erica Giles

Charlotte, North Carolina
profile_pic

Gary Schmidt

Clearwater, Florida
profile_pic

James Campos

Fort Worth, Texas
profile_pic

Jamie Carlson

Columbus, Ohio
profile_pic

Javier Garcia

Detroit, Michigan
profile_pic

Jeffrey Ferguson

Boston, Massachusetts
profile_pic

Jessica Jones

Arlington, Texas
profile_pic

Jonathan Buckley

San Diego, California
profile_pic

Joshua Melendez

Cincinnati, Ohio
profile_pic

Julie Gorman

Nashville, Tennessee
profile_pic

Julie Walker

Frisco, Texas
profile_pic

Katherine Summers

Chicago, Illinois
profile_pic

Katherine Woodard

Aibonito, Aibonito
profile_pic

Mathew Booker

Houston, Texas
profile_pic

Monique Foster

Houston, Texas
profile_pic

Nathan Kennedy

Tampa, Florida
profile_pic

Nicholas Downing

Palm Springs, California
profile_pic

Peter Martinez

Riverside, California
profile_pic

Phillip Lester

Anaheim, California
profile_pic

Rian Baker

Columbus, Ohio
profile_pic

Ruth Cummings

San Francisco, California
profile_pic

Ryan Brown

San Diego, California
profile_pic

Sahil Kumar

Spokane, Washington
profile_pic

Sahil Kumar

New York, New York
profile_pic

Sheena Lucas

Modesto, California
profile_pic

Sofia Chipen

Scottsdale, Arizona
profile_pic

Susan Day

Denver, Colorado
profile_pic

Test User-3

Seattle, Washington
profile_pic

Trey Lockwood

San Jose, California
profile_pic

Yvonne Beasley

Mesa, Arizona

Subscribe to the Agent Newsletter

Enter your information to download FREE Ebook!