Key Takeaways
- Understand each phase of the home buying journey, from preparation to closing.
- Avoid common pitfalls by asking questions, seeking expert advice, and setting a realistic budget.
Buying your first home can feel overwhelming, but knowing the right steps can make the journey smoother. With the right knowledge, you’ll build confidence as you navigate important decisions, from financial preparation to closing on your new home. Here’s what to expect and how to approach the process thoughtfully.
What Is the Home-Buying Process?
Overview of the journey
The home-buying process is a series of steps that guides you from the moment you decide to buy a home to finally holding the keys. Each stage, from initial research to closing, clarifies your options and protects your interests.
Who is involved?
Your journey typically involves several key players. You may interact with a real estate agent, mortgage lender, home inspector, appraiser, and closing agent. Each professional plays a distinct role—your agent helps you find properties, a lender guides you through financing, and inspectors ensure the home is in good condition.
Timeline expectations
Purchasing a home usually takes several weeks to a few months. The timeline can shift depending on your finances, the local market, and the complexity of the transaction. Staying organized and responsive helps keep the process moving smoothly.
Why Is Preparation Important?
Preparing finances
One of the most vital steps is getting your finances in order. This includes saving for a down payment, reviewing your credit, and estimating how much you can comfortably afford. Preparation ensures you start the process on solid footing.
Understanding your needs
Consider your lifestyle and future plans. Are you seeking a starter home, room for a growing family, or proximity to work? Listing your needs upfront keeps your search focused and reduces stress.
Setting realistic goals
Align your expectations with your budget and market conditions. Clear, realistic goals help prevent disappointment and support better decision-making as you search for homes.
Step 1: Assess Your Readiness
Evaluating your finances
Review your savings, debts, and monthly expenses. Lenders consider your income and credit when determining eligibility, so understanding your financial picture is essential.
Researching local markets
Take time to explore market trends in your target areas. Knowing average home prices and how quickly properties sell can help you make informed decisions and respond confidently when the right home appears.
When to consider home ownership
Homeownership is a significant commitment. Consider whether your job, family circumstances, and financial position support buying rather than renting. This reflection will prepare you for both the benefits and responsibilities of owning property.
Step 2: Explore Mortgage Basics
What is a mortgage?
A mortgage is a loan used to buy real estate, paid back over several years with interest. You agree to repay your lender in monthly installments, and the property acts as collateral until you repay the loan in full.
Types of home loans
Home loans fall into several categories, each with its own terms and requirements. Common types include fixed-rate mortgages (your interest rate stays the same), adjustable-rate mortgages (rates may change), and government-backed loans with different eligibility criteria.
How credit affects your options
Your credit history and credit score influence the types of loans you can qualify for, as well as the interest rates you might be offered. A higher score typically opens doors to more options, while a lower score may mean you need to take steps to improve your credit before applying.
Step 3: Find the Right Property
Home search tips
Begin your search with a clear list of needs and preferences. Online listings, open houses, and community walkthroughs can help you explore what’s available. Take notes, compare features, and track homes that catch your eye.
What should you prioritize?
Focus on essential features that match your lifestyle—such as location, size, and layout—rather than only cosmetic details. Include practical considerations like proximity to work or school and future resale value.
Visiting and evaluating homes
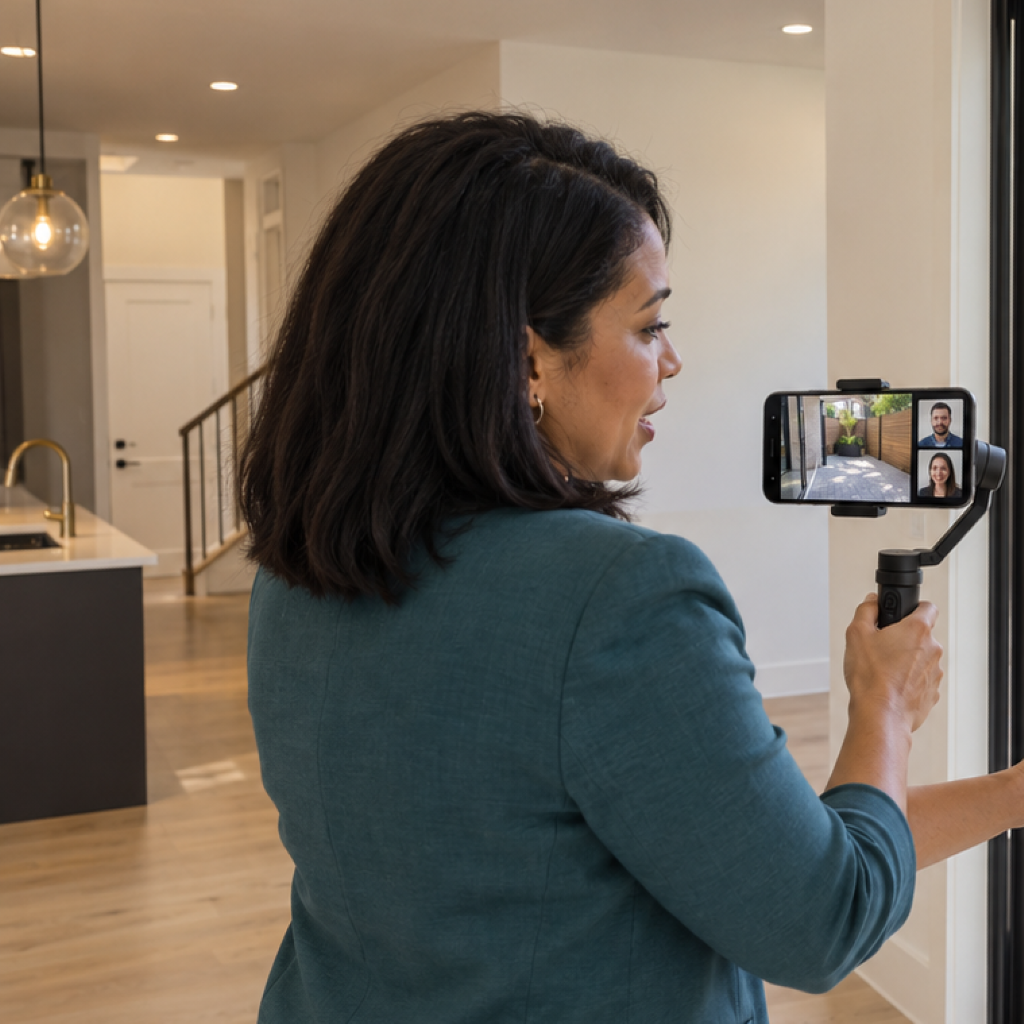
Touring properties in person (or virtually) offers valuable perspective. Look beyond surface appearances and pay attention to factors like natural light, overall condition, and required repairs.
Step 4: Make an Offer and Negotiate
Offer process explained
When you find a suitable home, submitting an offer is your next move. This formal proposal states your suggested purchase price and terms. The seller can accept, reject, or counteroffer.
Considerations before bidding
Check recent sale prices for similar homes, and consider whether multiple buyers are interested. Weigh your budget carefully—avoid emotional decisions that could push you beyond what you can comfortably afford.
Negotiating terms respectfully
Negotiation is common in real estate. Work with your real estate agent to request repairs or concessions based on inspections. Approach this stage with respect and flexibility to help both parties reach a fair agreement.
Step 5: Understand the Closing Process
What is closing?
Closing is the final meeting where ownership of the home transfers to you. It’s the culmination of all the steps leading up to this point.
Documents you’ll review
During closing, you’ll review and sign paperwork including the settlement statement, loan documents, and title forms. Review everything carefully and ask questions if something isn’t clear.
When do you get the keys?
Once you sign all documents and transfer funds, you’ll receive the keys to your new home. This officially marks the start of your ownership—and a new chapter in your life.
What Are Common Homebuyer Mistakes?
Overlooking hidden costs
The initial purchase price isn’t the whole story. Homebuyers sometimes overlook closing costs, property taxes, and maintenance expenses that add up over time.
Skipping inspections
Forgoing a home inspection may seem like a way to speed up the process, but it can lead to unpleasant surprises. Inspections reveal issues that could impact value, safety, or future costs.
Underestimating ongoing expenses
Monthly expenses go beyond your mortgage payment. Utilities, homeowners insurance, and repairs should all fit into your budget to avoid unwelcome financial strain.
How Can You Avoid Costly Errors?
Asking questions early
Never hesitate to ask for clarification at any stage. Understanding what you’re agreeing to can prevent costly misunderstandings later.
Seeking professional input
An experienced real estate agent and financial advisor can help you navigate complex paperwork and market trends. Their perspective is a valuable resource, especially if challenges arise.
Staying within budget
Commit to purchasing within your means. Thoughtful budgeting and restraint now will lead to greater peace of mind as a homeowner later.