Key Takeaways
- Understand the essential steps, documents, and costs involved in closing on a house.
- Be prepared to navigate common myths and avoid delays for a smoother closing process.
Many homebuyers are surprised to learn that closing on a house involves much more than just signing paperwork. The process includes a series of intentional steps, critical documents, and a mix of expected and unexpected costs. Understanding what to expect—and what to watch out for—can make your journey to homeownership smoother and less stressful.
What Does It Mean to Close on a House?
Definition of closing
Closing on a house is the final phase of the home-buying process, where legal ownership transfers from the seller to you. It is the culmination of weeks or months of research, negotiations, and waiting. During closing, you’ll review and sign a variety of documents, settle any outstanding balances, and receive the keys to your new property.
Importance in the buying process
This step is crucial because it legally secures your rights as the new homeowner. Closing officially ends the seller’s claims to the property and begins your responsibility for the mortgage, taxes, and property upkeep. A successful closing ensures all contractual obligations have been met, protecting both you and the seller.
Step 1: Review the Purchase Agreement
Key components to double-check
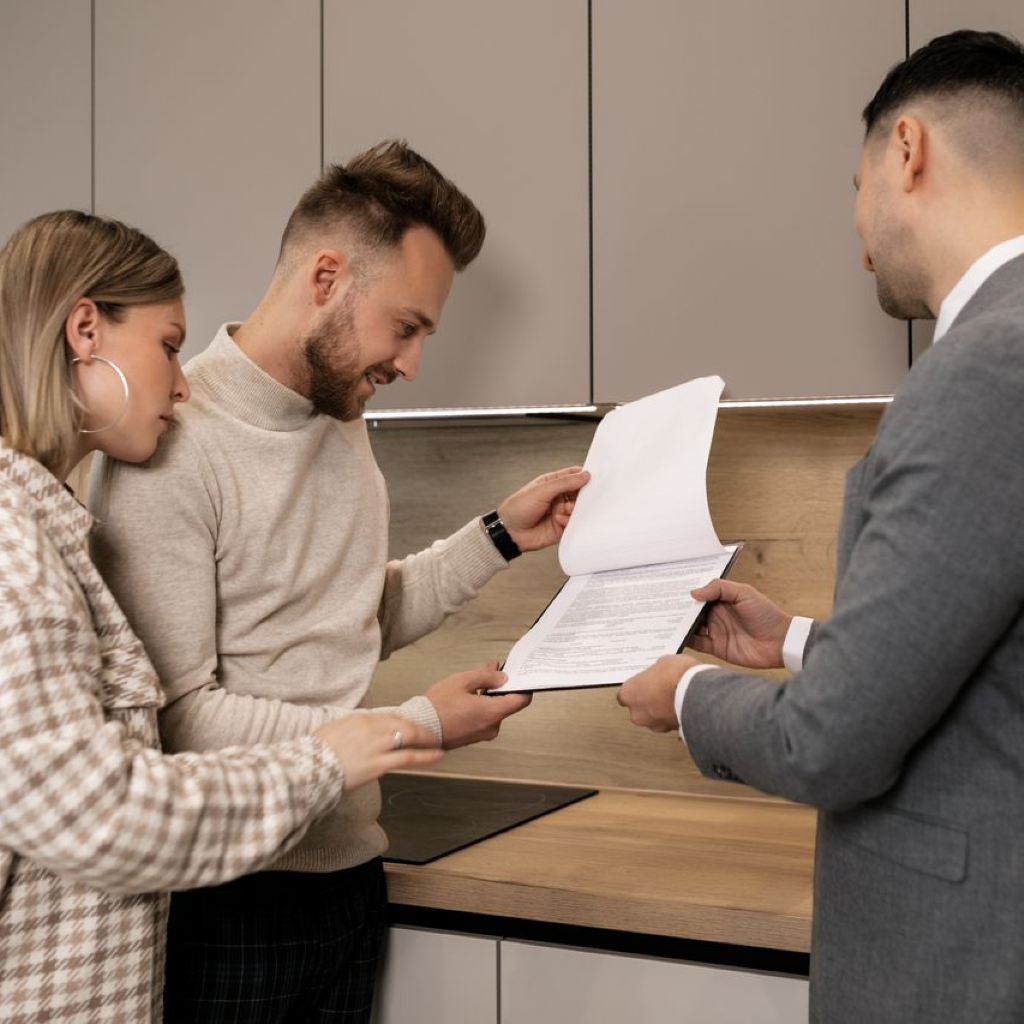
The purchase agreement is a binding legal document that outlines all terms of the sale. Before closing, carefully review specifics like the purchase price, contingencies (such as financing or inspection conditions), closing date, included fixtures, and any seller concessions.
What happens if changes are needed
If you notice discrepancies or need to update details—perhaps a change in financing or agreed-upon repairs—contact your real estate professional or attorney immediately. All parties must agree to any amendments in writing before closing proceeds.
Step 2: Secure Your Financing
Confirming loan approval
By now, you’ve likely obtained a mortgage pre-approval. However, final loan approval can depend on additional reviews—so make sure you provide any requested documents to your lender promptly.
Finalizing details with your lender
Keep communication lines open with your lender. Double-check loan terms, verify the interest rate, and confirm how much cash you’ll need at closing. Request a closing disclosure form in advance, which will summarize your loan terms and closing costs.
Step 3: Schedule the Home Inspection
Purpose of inspection
A home inspection is your opportunity to assess the property’s condition. It’s designed to uncover issues that could affect your decision to purchase or renegotiate certain terms.
Common findings and how to respond
Inspections may reveal concerns ranging from old plumbing to structural problems. If issues arise, discuss options with your real estate professional. You might request repairs, negotiate credits, or, in some cases, consider walking away if the problems are serious.
Step 4: Order the Home Appraisal
Why lenders require appraisals
Most lenders require an independent appraisal to confirm that the property’s value matches the purchase price. This protects both you and the lender against overpaying.
Possible outcomes and next steps
If the appraised value meets or exceeds the price, your loan moves forward. If it’s lower, additional negotiations may occur—potentially leading to new price terms, a larger down payment, or, in rare situations, cancellation of the deal.
What Documents Are Required at Closing?
Essential personal identification
Typically, you’ll need a government-issued photo ID (such as a driver’s license or passport) to verify your identity. Some closings require two forms of ID—check in advance to avoid surprises.
Key legal and financial paperwork
Expect to review and sign documents including the closing disclosure, settlement statement, promissory note, mortgage or deed of trust, and the deed transferring ownership. You may also see affidavits, tax documentation, and proof of homeowner’s insurance. Bring any paperwork your lender or closing agent requests.
What Costs Should Homebuyers Expect?
Typical closing costs explained
Closing costs are the fees and expenses due when you finalize your home purchase, typically ranging from 2% to 5% of the property’s price. Common charges include loan origination fees, title search and insurance, home appraisal, inspection fees, prepaid property taxes, and escrow deposits.
Ways to prepare for expenses
Ask your lender for a breakdown of costs in advance, so you’re not caught off guard. Save a little extra for incidentals; costs can vary depending on location, lender, and individual transaction details. Consider using a closing cost calculator to estimate your total out-of-pocket amount.
Common Myths About Closing on a House
Myth: Closing always happens fast
Many believe that closing is a quick, straightforward event. In reality, unexpected issues—such as title discrepancies or loan conditions—can delay the process by several days or weeks.
Myth: All fees are negotiable
While some closing costs may be negotiated, many are set by third parties or regulated by law. It’s wise to review your options, but understand that not every fee is flexible.
Myth: You’ll walk away with keys immediately
Although keys are usually provided at closing, some transactions include additional steps—like waiting for funds to clear or paperwork to be officially recorded—which can postpone move-in by a day or two.
What Can Delay or Complicate Closing?
Frequent reasons for delays
Delays can stem from paperwork errors, financing issues, title problems, last-minute negotiation changes, or even problems uncovered during a final walkthrough. Missing documents or incomplete approvals can also cause setbacks.
Tips for minimizing complications
Stay proactive: respond quickly to requests from your lender or closing agent, double-check all forms, and make sure you’ve scheduled everything (like inspections or appraisals) before the closing date. Keeping your documentation organized will help everything move smoothly.
How Can You Prepare for Closing Day?
Checklist for buyers
- Confirm your closing date, time, and location
- Bring required identification and payment method (such as a certified check or proof of wire transfer)
- Review the final closing disclosure and settlement statement
- Complete a final walk-through of the property
- Gather any additional paperwork requested by your lender or agent
Questions to ask your closing agent
- What forms of payment are accepted?
- Is another form of identification needed?
- When can I expect to receive the keys?
- Will any last-minute documents need to be signed?
- Who should I contact if delays arise?