Key Takeaways
- First-time home buyer programs can lower upfront costs and offer educational support, but come with certain restrictions.
- Evaluating personal finances and program eligibility is essential before deciding if these programs align with your needs.
Buying your first home is a major step—full of excitement, questions, and complex choices. First-time home buyer programs can ease the process, but you should understand how they work, who qualifies, and what benefits or drawbacks they may bring. Let’s walk through these topics so you can make a well-informed decision.
What Are First Time Home Buyer Programs?
Definition and purpose
First-time home buyer programs are resources designed to help individuals purchase their first residence. Their main purpose is to make homeownership more accessible, often by reducing financial barriers or providing educational support. Government agencies, nonprofits, and local housing organizations can sponsor programs. They generally focus on making homebuying more manageable for those who may not have significant resources or prior experience with the process.
Common types available
You’ll find a wide range of programs, each with its own focus. Some of the most common include:
- Down payment assistance: Grants or forgivable loans intended to help buyers cover part or all of the required down payment.
- Reduced down payment mortgages: Government-backed loans (such as those from the FHA or VA) that allow buyers to purchase with less cash upfront.
- Closing cost assistance: Support to cover expenses like appraisals, title searches, or insurance.
- Home buyer education courses: Free or low-cost classes that walk you through each stage of the home-buying process.
- Tax incentives: Some programs may offer tax credits or deductions for first-time buyers.
Who Qualifies as a First Time Buyer?
Typical eligibility criteria
Being a “first-time buyer” is not always as straightforward as it sounds. Most programs define the term as someone who hasn’t owned a home in the last three years. Common eligibility requirements you’ll encounter may include:
- You haven’t owned a principal residence in three years or more.
- The home you’re purchasing will serve as your primary residence.
- Income below certain limits, which vary by location and household size.
- Purchase price restrictions on the property.
- Completion of an approved home buyer education course.
Special circumstances that count
There are some exceptions worth noting:
- Previous homeowners: If you’ve only owned a home with a former spouse, or in certain cases after a divorce, you may qualify again as a first-time buyer.
- Displaced homemakers or single parents: You may be eligible even if you previously owned property with a partner.
- Other exceptions: Certain programs welcome buyers who have only owned property not considered a permanent residence, such as RVs or mobile homes.
Pros of Home Buyer Programs
Lower down payment requirements
One of the biggest draws of these programs is the potential for a lower down payment. Traditional mortgages may require up to 20% down, but first-time buyer programs often lower this barrier, making homeownership more possible for those without significant savings.
Potential closing cost support
In addition to down payment help, some programs offer grants or low-interest loans to assist with closing costs. That means you could need less cash on hand to finalize your home purchase.
Educational assistance resources
Many first-time buyer options include access to homeownership education. These courses guide you through budgeting, applying for a mortgage, and maintaining your new property—helping you make smart, informed decisions and preparing you for long-term success as a homeowner.
What Are the Cons to Consider?
Income and property limitations
Most programs set maximum income levels and limit the value of the home you can buy. This can limit your housing options and make it harder to buy in high-demand or high-priced neighborhoods.
Program restrictions explained
Some programs are only open to first-time buyers, or to properties that meet specific criteria (such as being in certain locations or in need of rehabilitation). There may also be limits on the types of loans you can use, or rules requiring you to live in the home for a set number of years to avoid repaying benefits received.
Ongoing obligations post–purchase
After buying, you may face additional requirements. For instance, relocating or selling the property within a certain timeframe could trigger repayment of grants or credits. Staying compliant with these rules helps you avoid unexpected financial repercussions.
How Can You Apply for These Programs?
Where to find program information
Start your search with local housing agencies or government websites—many have special sections for first-time buyers or offer interactive questionnaires to guide you. Nonprofit housing organizations or HUD-approved counseling agencies also provide information about available options. A mortgage professional can help you understand which programs may fit your needs, but always verify details through independent sources.
Documents typically needed
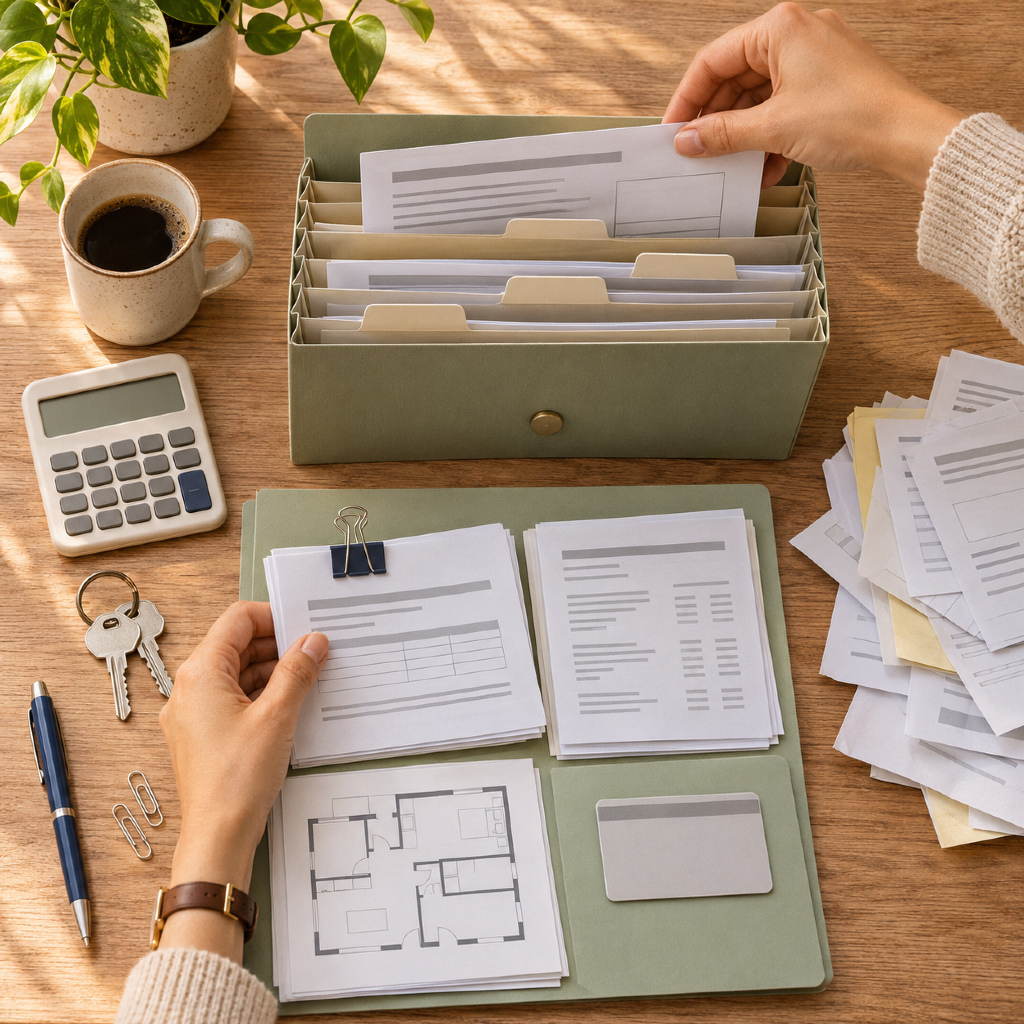
Applying generally requires documentation to verify your identity, finances, and housing status. Expect to provide:
- Recent pay stubs or income statements
- Tax returns
- Bank account and asset information
- Employment verification
- Proof you haven’t owned a home within the program’s required timeframe
- Completion certificate for any mandatory home buyer education
Each program has its own checklist, so review requirements carefully before preparing your application materials.
Are Home Buyer Programs Right for You?
Assessing your personal situation
Take time to reflect on your financial picture—consider your income, savings, monthly expenses, and future plans. If you’re struggling to save a down payment or qualify for standard loan products, these programs may be particularly valuable. Weigh the benefits against any restrictions or obligations, and factor in your long-term housing goals.
Alternatives to consider
If you don’t meet eligibility or prefer fewer program constraints, you still have options:
- Conventional mortgages with low down payment features
- State-sponsored programs outside “first-time” requirements
- Assistance from family or other financial resources
- Exploring different housing types or locations to meet your goals
Always compare the pros and cons of each route, and seek out unbiased educational materials before making decisions.